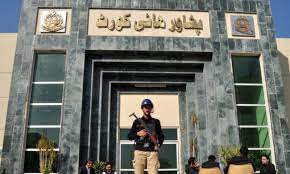
PESHAWAR: Peshawar High Court has declared that Federal Excise Duty (FED) couldn’t be imposed on green leaf and hand-stemmed tobacco unless it has been processed and converted by a green leaf threshing (GLT) unit.
A bench consisting of Justice Syed Arshad Ali and Justice Mohammad Faheem Wali disposed of 14 petitions filed by some tobacco growers, tobacco companies and GLT units, challenging the levy of FED on hand-stemmed tobacco, sealing of warehouses and godowns of some of the petitioners and confiscation of ‘un-manufactured’ tobacco and machinery present therein.
The bench issued multiple directives in its 29-page detailed judgement wherein it discussed threadbare different provisions of the FED Act, 2005, and its applicability to manufactured and un-manufactured tobacco.
The court directed relevant authorities to release the seized tobacco, vehicles, equipment and records and de-seal the premises and machinery forthwith.
Court orders de-sealing of several premises of tobacco growers, companies
However, it directed where authorities maintained that any seized stock had been processed by a GLT unit, they could retain the identified goods for up to 15 days to pass a reasoned order after providing the affected party an opportunity of hearing.
The bench also set aside show-cause notices and orders issued to the petitioners to the extent that they sought to impose FED on hand-stemmed, stemmed or green leaf tobacco not processed through a GLT unit. It clarified that any remaining proceedings relating to sales tax, penalties or confiscation would be decided in accordance with law.
The court also set aside compulsory registration notices issued on the ground that hand-stemming constituted manufacturing, while clarifying that authorities could initiate fresh proceedings if material established that a person was operating a GLT unit.
Granting relief to petitioners, the bench ordered the release of 3,375-kg of hand-stemmed tobacco and the vehicle, belonging to one of the petitioners M/s Pak Hills Tobacco Company, while setting aside the FED demand. It, however, left the question of any sales tax liability on the consignment to be determined in accordance with law.
The court also set aside the show-cause notice demanding FED of Rs123.992 million from a petitioner M/S Royal Tobacco Company. It ordered that its godowns should be de-sealed and the 628,145-kg of hand-stemmed tobacco and 130,000-kg of green leaf tobacco should be released.
However, the bench maintained that if the respondents including the Commissioner Inland Revenue assert that any goods seized from the petitioner were not hand-stemmed tobacco but unmanufactured tobacco processed and converted by a GLT unit, the competent authority should, within 15 days of the receipt of that judgement and after affording the petitioner concerned an opportunity of hearing, pass a reasoned order identifying such goods by quantity and description and stating the material on which that finding rested.
Advocates Ishtiaq Ahmad Senior and Isaac Ali Qazi appeared for the petitioners and contended that hand-stemmed tobacco remained a constitutionally protected agricultural produce exempted from federal taxation and that the impugned levies and search warrants were illegal and unconstitutional.
The assistant attorney general, Bilal Ahmad Durrani, and lawyers appearing for respondents including federal finance ministry and Commissioner Inland Revenue contended that in an earlier judgement of the court the levy of FED on unmanufactured tobacco was held to be in accordance with the Constitution.
They stated that the petitioners had portrayed large-scale commercial processing and storage of unmanufactured tobacco from undeclared godowns as an exempt agricultural activity of ‘hand-stemming’, whereas sections 2(16) and 2(24A) of the Act of 2005 expressly brought such drying, cutting and threshing within the definition of “manufacture”, attracting an adjustable FED of Rs390 per kilogram.
The bench disagreed with the respondents’ contention and ruled that green leaf tobacco and hand-stemmed tobacco, which had not undergone processing and conversion through a GLT unit, did not fall within the definition of “unmanufactured tobacco” under Section 2(24A) of Federal Excise Act, 2005.
“Consequently, such tobacco is not liable to FED under Section 3 of the Act,” the bench ruled.
The bench ruled that hand-stemming, even when carried out with the use of tools or machinery, could not by itself be treated as a manufacturing process to justify the levy of federal excise duty.
The bench discussed the various stages involved in the cultivation, post-harvest processing and eventual use of Flue-Cured Virginia (FCV) tobacco, one of the principal varieties used in cigarette manufacturing.
The bench observed that although unmanufactured tobacco had previously been subjected to FED under the Act of 2005, the expression was defined for the first time through Finance Act, 2018, which inserted Clause (24A) in Section 2 of the Act.
It stated that under the said provision, “unmanufactured tobacco” meant tobacco usable for the manufacture of cigarettes, as manufactured by GLT units after processing and conversion of tobacco green leaf. The definition thus identifies the nature of the tobacco, its intended use, the process through which it comes into being and the unit by which that process is undertaken.
The bench observed that the levy in question was tied to the conversion of tobacco green leaf into unmanufactured tobacco through processing by a GLT unit.