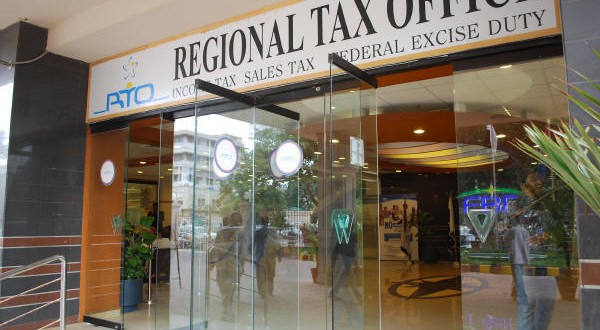
KARACHI: With the aim to dispose audit cases and ensure recovery of revenue, the Corporate Regional Tax Office (CRTO), Karachi has assigned jurisdictions.
The CRTO assigned audit jurisdictions to four units under income tax, sales tax, federal excise and wealth tax.
Under Income Tax, the units shall exercise:
- Processing cases selected for audit under Section 177 of Income Tax Ordinance, 2001;
- Provisional assessment under section 23;
iii. Best judgment assessment under clause (c) and (d) of Section 121;
- Amendment assessment under section 122 other than section 122(5A), and exercise of powers and functions, under any specific provisions of law and rules provided in the ordinance and schedules thereto in respect of audit and assessment;
- Assessment under section 143 and 144;
- Giving effect to appeal orders, re-assessment of set-aside/annulled orders and rectification of mistakes under section 221 relating to assessment including provisional assessment, best judgment assessment and amended assessment;
vii. Computation of income chargeable to tax and determining tax payable thereon and allowing credit of taxes paid or adjustment of refund due under Part-IV of Chapter-X or under any other specific provision provided under the Ordinance and Rules;
viii. Exercise of powers to determine income under ‘Anti Avoidance’ provisions contained in Chapter VII of the Ordinance;
- Perform any other function in determining and computing income chargeable to tax and impose correct tax payable under the ordinance including;
- Issuance of notices/intimation letters/IDR, PNR and preparation of audit report in the cases selected for audit;
- Follows-up of the said notices/letters;
xii. Examination of Accounts;
xiii. To conduct spot visits and enquiries;
xiv. Issuance of assessment / amended assessment orders/ demand notices;
- Initiation of penalty under Part-X / prosecution proceedings;
xvi. Utilization of information provided by obtained from complaints, external/internal audit authorities, other agencies;
xvii. Any other function ancillary to audit.
The RTO assigned jurisdictions under Sales Tax included:
- Audit of registered persons;
- Audit of selection and allocation strategy;
iii. Risk based audit through profiling and analysis;
- Review of audit reports for quality and integrity;
- Recovery of undisputed liability detected during audit;
- Monitoring of audit schedule, etc;
vii. Maintenance and analysis of audit records and audit related database;
viii. Matters relating to external audit (Revenue Receipt Audit) including Public Accounts Committee;
- Post Refund Audit;
- Audit Management Cell functions;
- Investigative audit after action under Section 38 of the Sales Tax Act.
The jurisdiction over federal excise laws, included:
- Audit of registered persons;
- Maintenance and analysis of audit records and audit related database;
iii. Matters relating to external audit (Revenue Receipt Audit) including Public Accounts Committee;
- Investigative audits;
- Any other audit function given by commissioner, for achieving the purpose of Federal Excise Act 2005.
The jurisdiction order also include Wealth Tax Act, 1963 (Repealed) and Finance Act, 1989 (CVT) such as: exercise all powers (except recovery and appeals) under the Wealth Tax Act, 1963 (Repealed) or the Finance Act, 1989.
Jurisdiction of Audit Unit -01:
All cases of companies of following sectors other than those specifically assigned to LTU/LTU-II, Karachi whose place of business is situated within the limits of former Civil Division Karachi of the Province of Sindh:
- Commercial Banks, Non-Banking Financial Institutions, Investment Banks including Investment Companies, Security; Companies/Agencies, Insurance Companies;
- Builders, Real Estate developers and Cooperative Housing Societies; and
Directors of all cases falling in the above sectors.
Cases of classes of cases or persons or classes of persons or areas assigned specifically by commissioner from time to time.
Jurisdiction of Audit Unit – 02:
All cases of companies of following sector other than those specifically assigned to LTU/LTU-II, Karachi whose place of business is situated within the limits of former Civil Division Karachi of the Province of Sindh:
- All residual companies not assigned to LTU/LTU-II Karachi or not falling in any of the designated sectors assigned by the FBR whose name begins with alphabet A; and
Directors of all cases falling in the above stated sectors.
Cases or classes of cases or persons or classes of persons or areas assigned specifically by commissioner from time to time.
Jurisdiction Audit – 03:
All cases of companies of following sector other than those specifically assigned to LTU/LTU-II, Karachi whose place of business is situated within the limits of former Civil Division Karachi of the Province of Sindh:
- Educational/Training/Vocational Institutions;
- All residual companies not assigned to LTU/LTU-II, Karachi or not falling in any of the designated sectors assigned by the FBR whose name begins with alphabet B & C; and
Directors of all cases falling in the above stated sectors.
Cases of classes of cases or persons or classes of persons or areas assigned specifically by commissioner from time to time.
Jurisdiction of Audit Unit – 04:
All cases of companies of following sectors other than those specifically assigned to LTU/LTU-II, Karachi whose place of business is situated within the limits of former Civil Division Karachi of the Province of Sindh:
- Manufacturer, exporter, and importer of auto and auto parts;
- All residual companies not assigned to LTU/LTU-II Karachi or not falling in any of the designated sectors assigned by the FBR whose name begins with alphabet D & E; and
Directors of all cases falling in the above stated sectors.
Cases of classes of persons or areas assigned specifically by commissioner from time to time.